
FTAI — Engine modules, fleet life and the cash test
Update — October 30, 2026. This is October 29 research; price and options references are dated snapshots. The Q3 release is already out, not a future catalyst: FTAI reported $977.7M revenue, $348.3M adjusted EBITDA and 311 modules. Power remains pre-delivery. The Q3 supplement reports nine-month operating cash flow of −$333.0M, versus −$265.3M in H1: Q3 alone was about −$67.7M. Its roughly 15% market share is a management estimate using annualized Aerospace revenue over estimated maintenance spend, not a count of installed engines. The December 10 investor meeting remains ahead.
$FTAI rebuilds engines that airlines are keeping in service longer. Its October 29 Q3 2026 release reported Aerospace Products revenue growth of 76%. The opportunity is faster access to usable engine modules; the key test is whether inventory investment becomes cash.
What Changed — older engines stay in service
Many airlines are operating older fleets longer than planned. Boeing and Airbus cannot build narrowbodies fast enough, and FTAI's management told investors on October 29 that new-generation Boeing 737 and Airbus A320neo slots are unavailable until 2032 and beyond. The newer engines on the jets that do arrive, the CFM LEAP and the Pratt & Whitney GTF, spend far more time in the shop than the engines they replace. So the previous generation, the 737NG and A320ceo with their CFM56 and V2500 engines, keeps flying. $GE, which builds the CFM56 with Safran, now expects only 1.5% to 2% of the CFM56 fleet to retire this year, down from the 2% to 3% it guided in January and the 3% to 4% it once planned on.
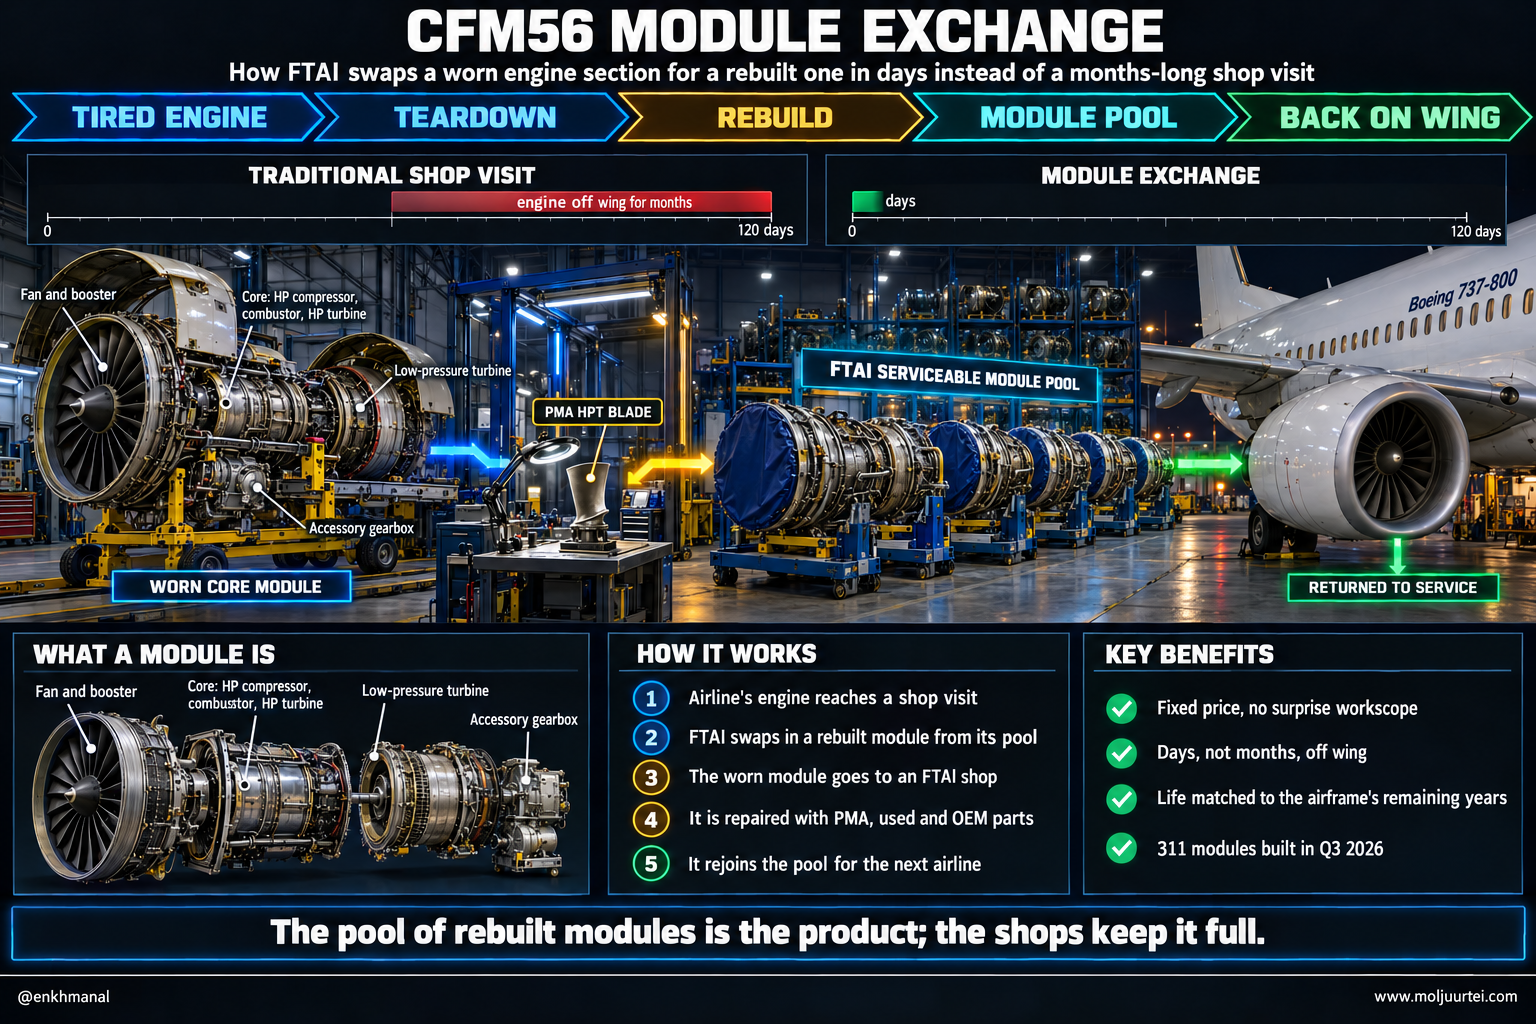
Start here. A jet engine is a machine that sucks in air, squeezes it, burns fuel in it and blows it out of the back faster than it came in. A turbofan is a jet engine with a large fan on the front, driven by a turbine at the back, that pushes most of its air around the hot core instead of through it, which is what makes it efficient. A module is one of the few big sections a turbofan is built from and can be separated into: on a CFM56 that means the fan and booster, the core (high-pressure compressor, combustor and high-pressure turbine), the low-pressure turbine and the accessory gearbox. A shop visit is what happens when one section wears out or a life-limited part, a disk or shaft certified for a fixed number of take-offs, reaches its limit: the whole engine comes off the wing and goes to a repair shop. A module exchange is the alternative: instead of waiting for your own section to be repaired, you swap it for one somebody already rebuilt.
That last rung is the whole business. A shop visit is slow because it is a queue: the engine waits for an induction slot, then for parts, then for a test cell, and the airline either leases a spare engine or parks a jet until it returns. When every operator is keeping old engines alive at once, the queue lengthens exactly when the fleet leans on it hardest. The incumbent answer is the overhaul shop, run by the engine maker, by an airline's own maintenance arm, or by an independent such as $SARO or Lufthansa Technik. It works, it is certified, and it restores serviceability within approved part-life limits. Its limit is that it restores more life than an old airframe can use, at OEM part prices, on the shop's calendar. A 737NG with five years left does not need an engine rebuilt for another fifteen.
The shift rewards whoever already holds a stock of serviceable modules and the shops to keep refilling it. That is $FTAI Aviation, and it has spent five years building exactly that.
Thesis — the module pool behind an aging fleet
$FTAI owns the largest independent pool of rebuilt CFM56 modules, sells engine time to airlines at a fixed price in days instead of months, and plans to reuse the same engine cores as 25-megawatt power turbines for data centers.
Business & Backdrop — one segment does the work
FTAI makes money three ways, and one of them now does nearly all of it. Aerospace Products buys tired CFM56 and V2500 engines and whole aircraft, strips them into modules, repairs the modules in its own shops and sells or exchanges them to airlines and lessors, which it calls MRE (maintenance, repair and exchange). Aviation Leasing used to own planes and lease them; it is now mostly a manager of other investors' planes through the Strategic Capital Initiative, funds in which FTAI holds a 19% stake in the first vehicle, earns servicing fees, and supplies the engine work. FTAI Power, which has no revenue yet, converts CFM56 cores into gas turbines.
The table retains the stated dates and units.
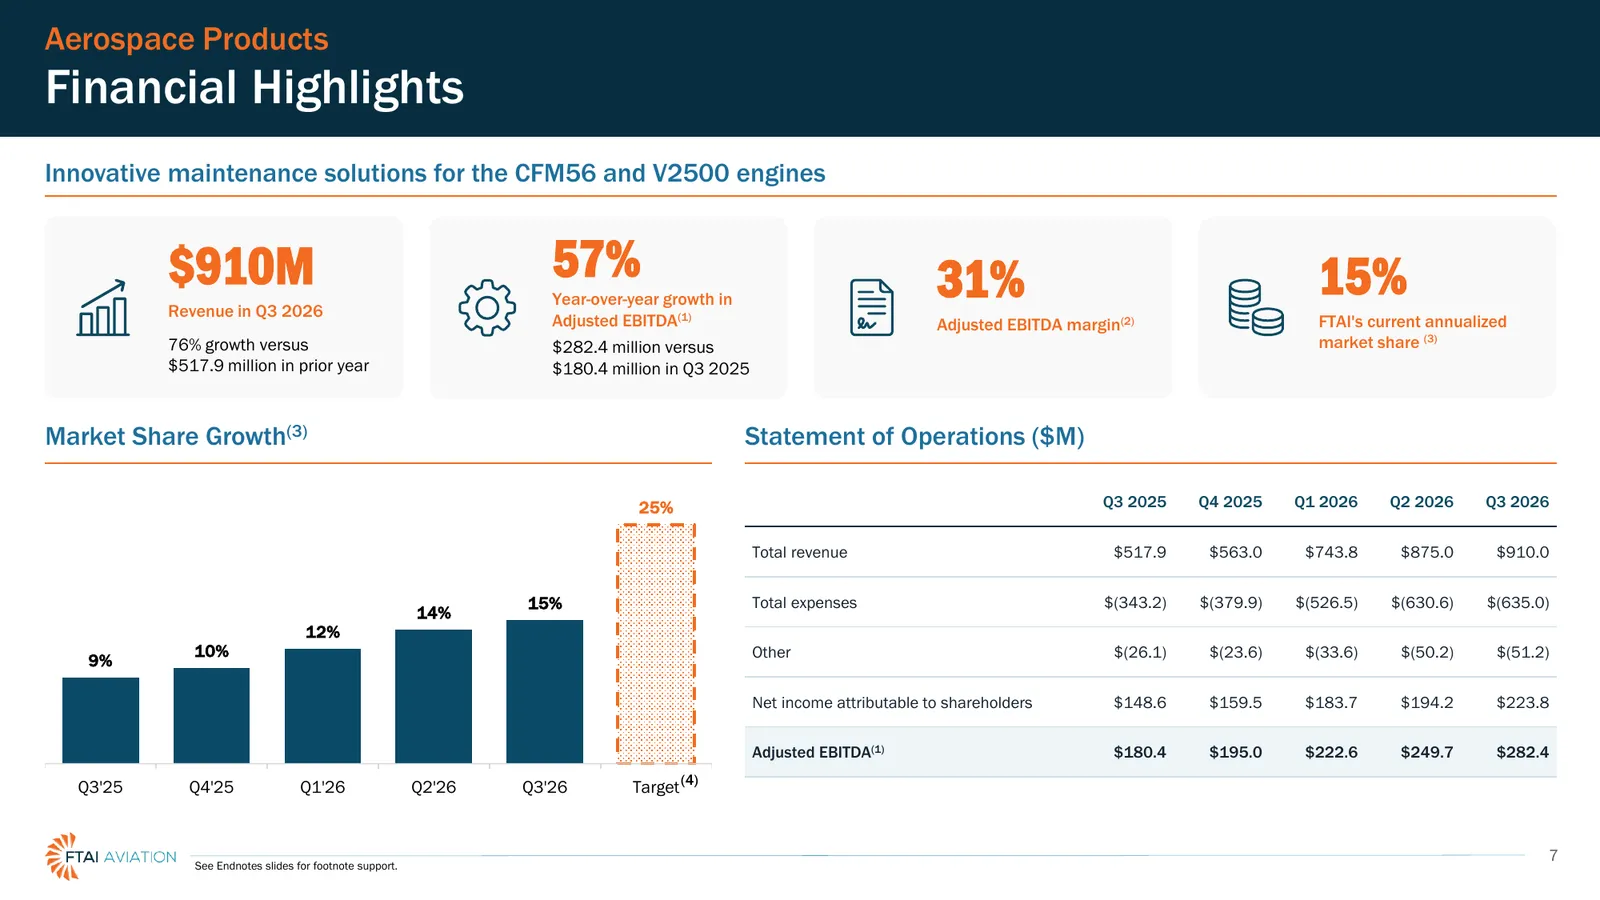
Aerospace Products is now 93.1% of revenue, up 15.5 points in a year, and it produced more than all of the company's revenue growth while leasing shrank by design. So this is a single-engine story wearing a three-segment income statement, and the thesis lives or dies on module volume and module margin. Segment Adjusted EBITDA tells the same story: $282.4 million from Aerospace Products in Q3 against $104.0 million from Leasing and minus $38.1 million from corporate.
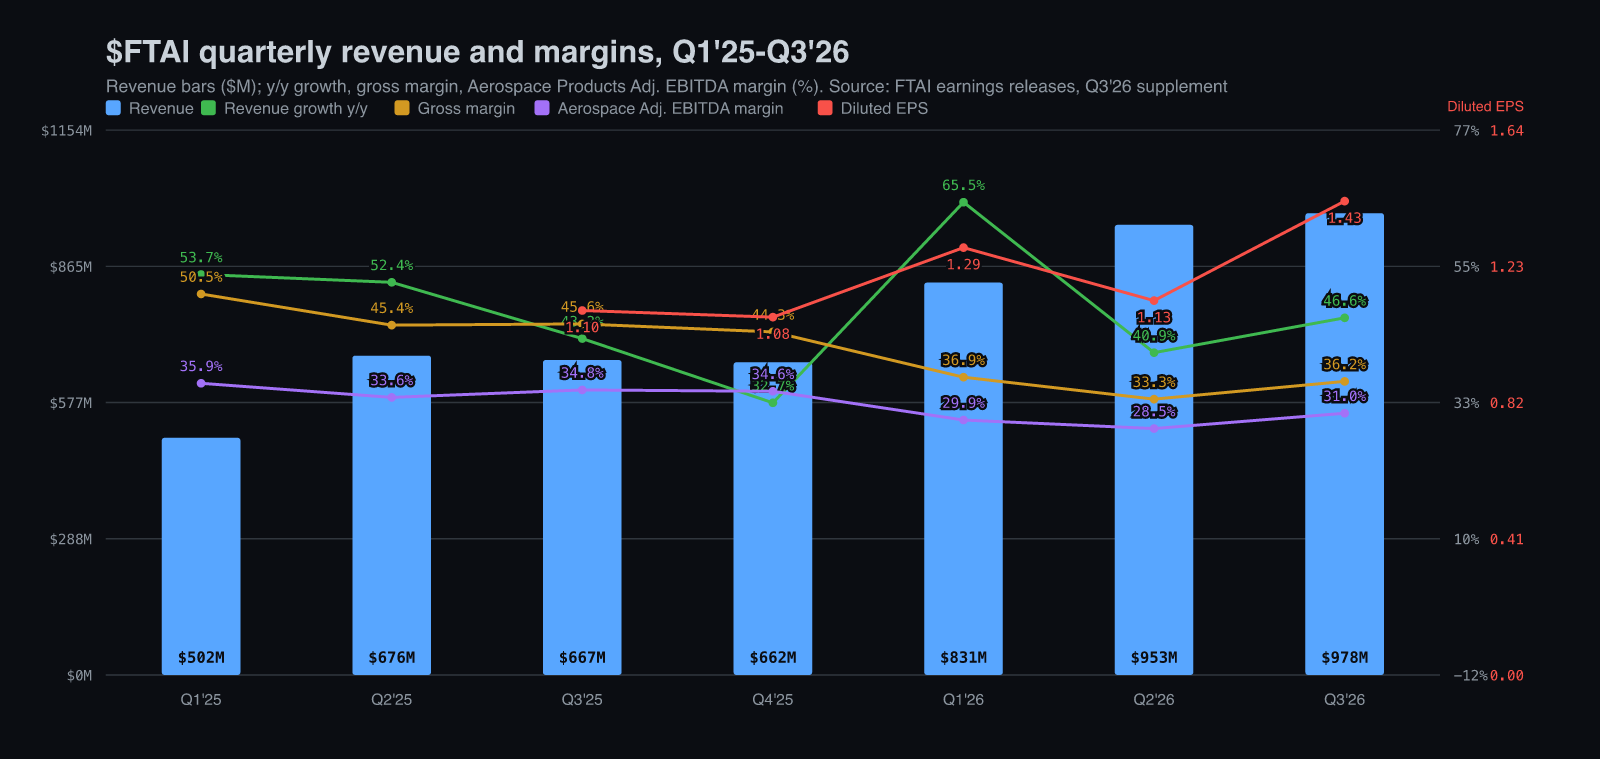
Revenue has compounded hard and margins have come down as the mix moved to heavier work. Revenue was $455.8 million in FY21, $708.4 million in FY22, $1,170.9 million in FY23, $1,734.9 million in FY24 and $2,507.4 million in FY25. Gross margin ran 64.9% in FY22, 57.1% in FY23, 52.4% in FY24 and 46.2% in FY25, as product sales replaced lease income. Aerospace Products' Adjusted EBITDA margin held near 35% for three years (35.2%, 35.2%, 34.7%) and then reset lower in 2026.
The quarterly series shows where the reset happened. Revenue was $502.1 million in Q1'25, $676.2 million in Q2'25, $667.1 million in Q3'25, $662.0 million in Q4'25, $830.7 million in Q1'26, $953.1 million in Q2'26 and $977.7 million in Q3'26. Gross margin fell from 50.5% to a 33.3% trough in Q2'26 and recovered to 36.2% in Q3'26; the Aerospace Adjusted EBITDA margin went 35.9%, 33.6%, 34.8%, 34.6%, then 29.9%, 28.5% and 31.0%.
The suppliers on the other side of the invoice confirm the demand. $GE's commercial engines unit grew services revenue 17% in Q3 with spare parts up more than 20%, said CFM56 workscopes were stable, and cut its CFM56 retirement estimate to 1.5 to 2 points. Safran reported civil engine spare parts up 17.0% in dollars in Q3, slower than the first half and driven by CFM56 pricing and better part availability. $SARO, one of the largest independent overhaul shops, grew Engine Services revenue only 4.0% in Q2 to $1,405.1 million. Read together: OEM parts are getting dearer, which raises the cost of a traditional shop visit, and the independents are capacity-bound. That is the gap FTAI sells into, and it is also FTAI's own input-cost problem.
There are four ways the industry can get more engine time out of an aging fleet, and it helps to see them side by side. More overhaul capacity at the OEM networks and independents adds slots, but $GE is pointing its new capacity at LEAP. Spare-engine leasing from $WLFC, $AER and others buys time without fixing anything. Cheaper parts, from approved aftermarket makers such as $HEI and from used serviceable material, cut cost without cutting the wait. Module exchange attacks the wait directly. FTAI does the fourth and owns pieces of the second and third, which is why it can quote a fixed price and a short turnaround at the same time.
Technology & Moat — feedstock, shops and parts
FTAI's product is not a new engine; it is a rebuilt section of an old one, delivered from stock with paperwork that lets it fly. Making that product at scale takes three things at once. The first is feedstock: FTAI buys whole engines and retired aircraft, including ten unserviceable 737s from WestJet this quarter whose engines go straight into the module network. The second is repair capacity: six CFM56 overhaul facilities, with Rome, Lisbon and Montreal expanding and new shop partnerships with Garuda Maintenance Facility AeroAsia in Jakarta and EgyptAir, plus piece-part repair at Pacific Aerodynamic in California and the Bauer joint venture in Connecticut. The third is cheaper parts: a multiyear materials agreement with CFM for OEM parts, thrust upgrades and component repair, and a joint venture with Chromalloy for FAA Parts Manufacturer Approval parts, replacement parts approved for flight but made by someone other than the engine maker.
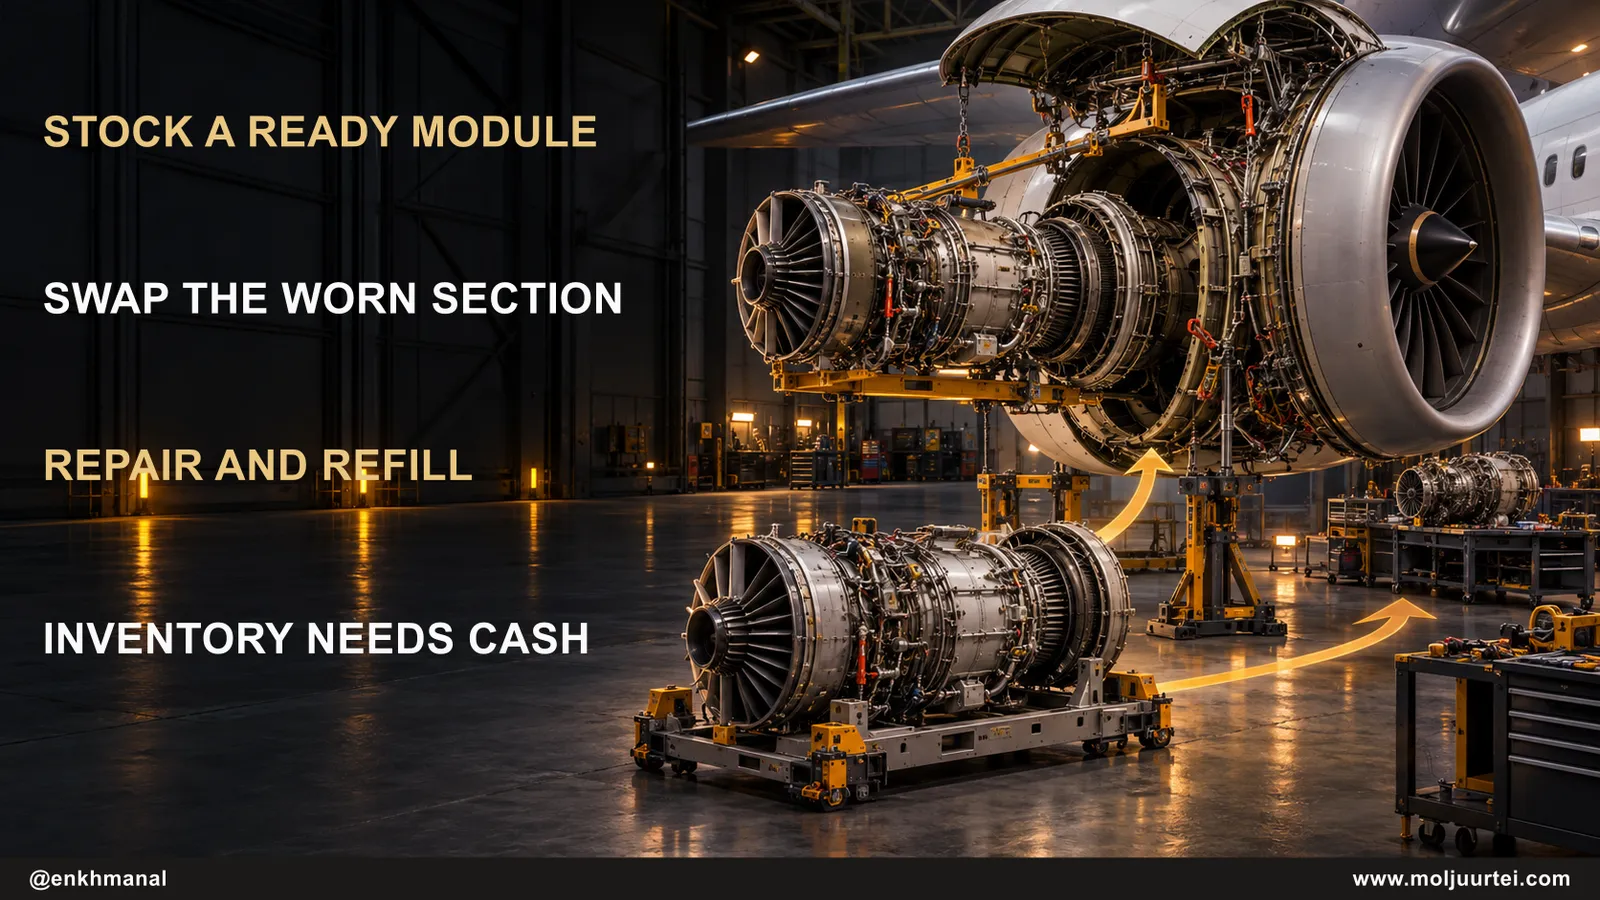
The approved-parts piece is where the margin comes from. Management said in April that five parts are in the Chromalloy program, three are approved, and those three represent about 80% of the planned cost savings; the first part approved was the high-pressure turbine blade. A competitor can buy a building and tooling. It cannot quickly assemble a pool of hundreds of matched, documented modules, a parts cost base below OEM list and airline trust that a swapped module will behave.
Our ultimate goal is to provide engine exchanges for narrowbody engines to the entire industry, such that, hopefully in many years to come, no one ever thinks about doing their own shop visit.
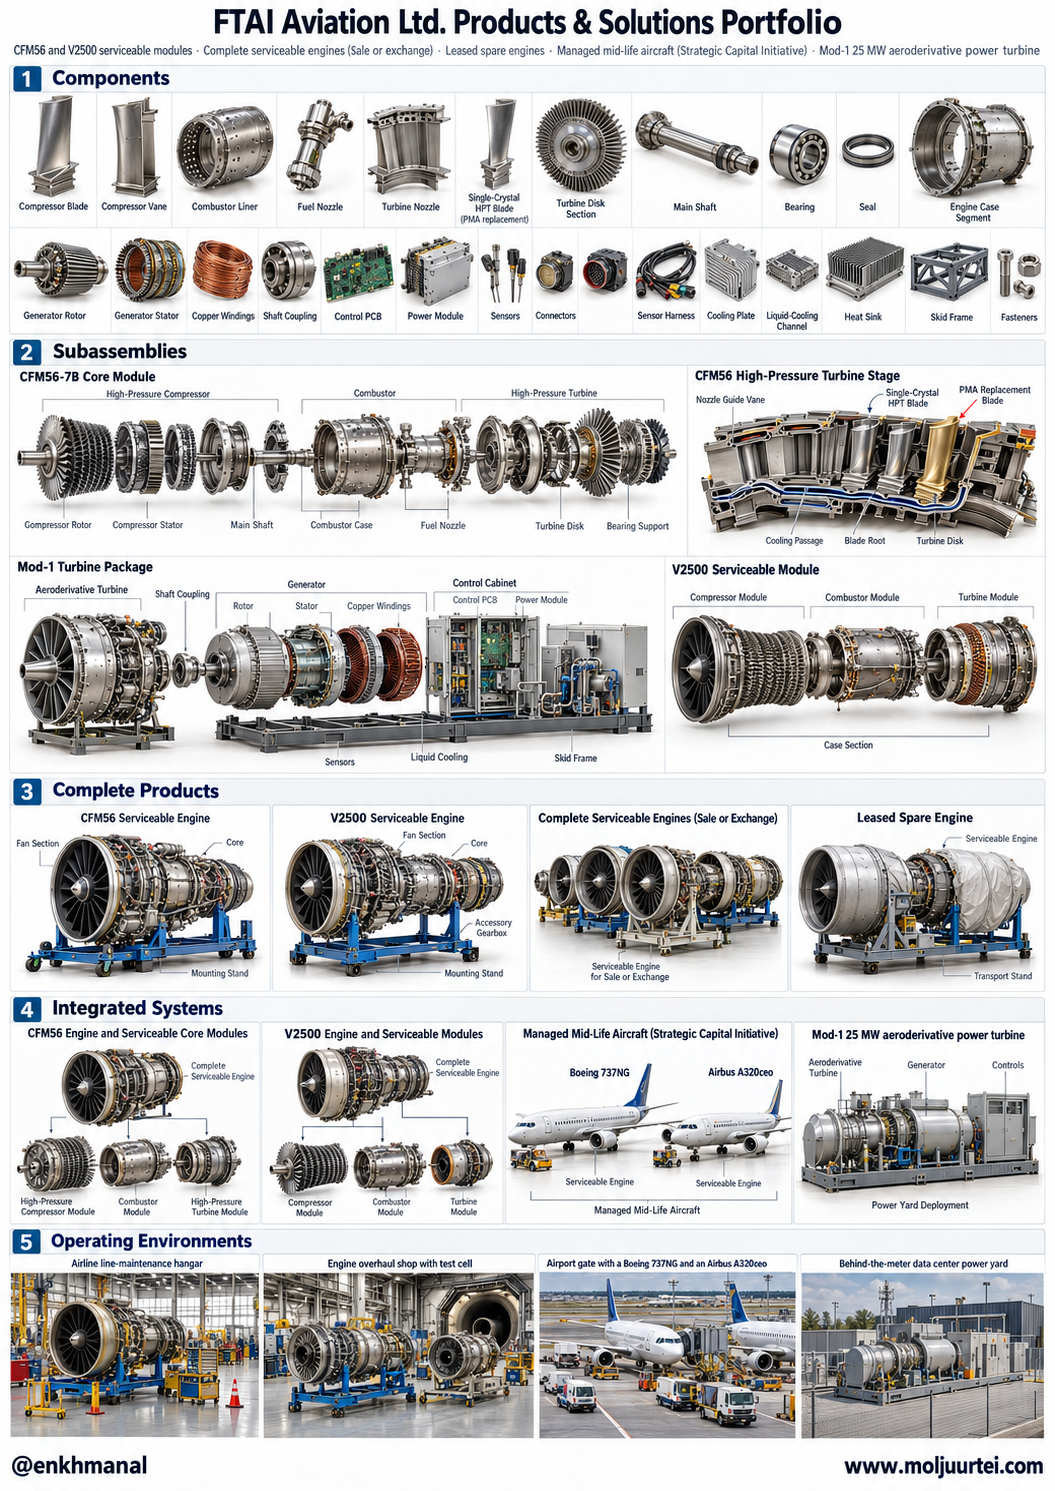
The poster below draws that mechanism end to end: a worn core module comes off the wing, a rebuilt one goes on, and the worn one enters the repair loop to become the next customer's part.
The portfolio poster compares the existing modules, complete engines, leased spares and managed aircraft with the planned Mod-1 turbine. Power has not yet generated revenue.
Roadmap & R&D — 1,700 modules and a turbine factory
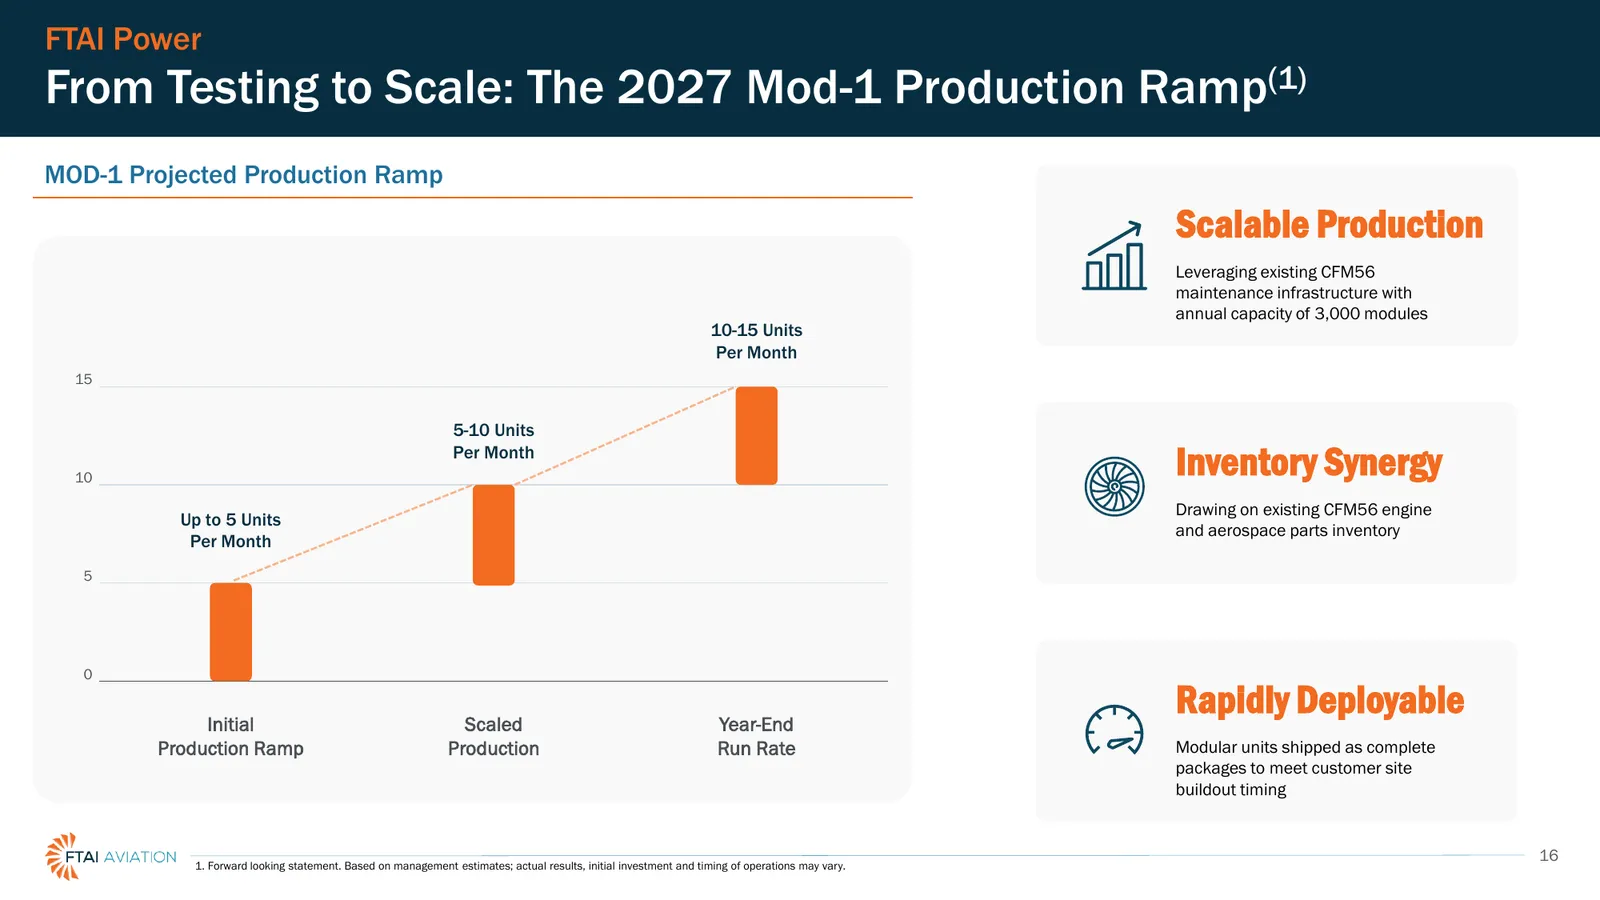
The money is going into two lines that share one engine. In Aerospace Products the plan is 1,200 modules this year (877 built through September) and 1,700 in 2027, against 3,000 a year of installed capacity, with $50 to $60 million going into tooling and a test cell at the acquired shops. In Power, the Mod-1 completed its critical tests this quarter at 25 MW peak and 23.1 MW continuous baseload on both natural gas and liquid fuel, and production starts on the same Montreal floor that rebuilds modules.
Power is the second use of the same core. FTAI says it has more than 100 Mod-1 units under contract with customers in the U.S. and Canada, mostly for 2027 delivery, including the $1.465 billion order announced in July through J&F Power Systems, its packaging venture with China's Jereh Group. It guides $7 to $8 million of EBITDA per unit and $450 to $750 million of Power EBITDA in 2027. The pitch is modular redundancy: a data center islanded from the grid needs spares, and backing up a 25 MW unit takes far less idle capital than backing up a 300 MW frame.
The Setup — why it is mispriced: the fall and what the print fixed
The stock halved between February and October for three reasons, and only one of them is about the business model. The run to $323.51 in February priced the Power launch before a single turbine had been tested. Then management walked back two numbers it had set: in October 2025 it told investors Aerospace margins would grow to 40% plus in 2026, and from April the quarters printed near 30% as large airlines bought full restorations; in July it cut 2026 Leasing EBITDA to $475 million from $575 million and total adjusted free cash flow to $878 million, and Q2 consolidated Adjusted EBITDA, as first reported, fell to $291.4 million from $347.8 million a year earlier. The stock went from $270.50 at the end of June to $206.00 at the end of July. Through September and October, higher jet fuel, worries about airline cash, and questions over the Chinese packaging partner took it to about $147 on October 23.
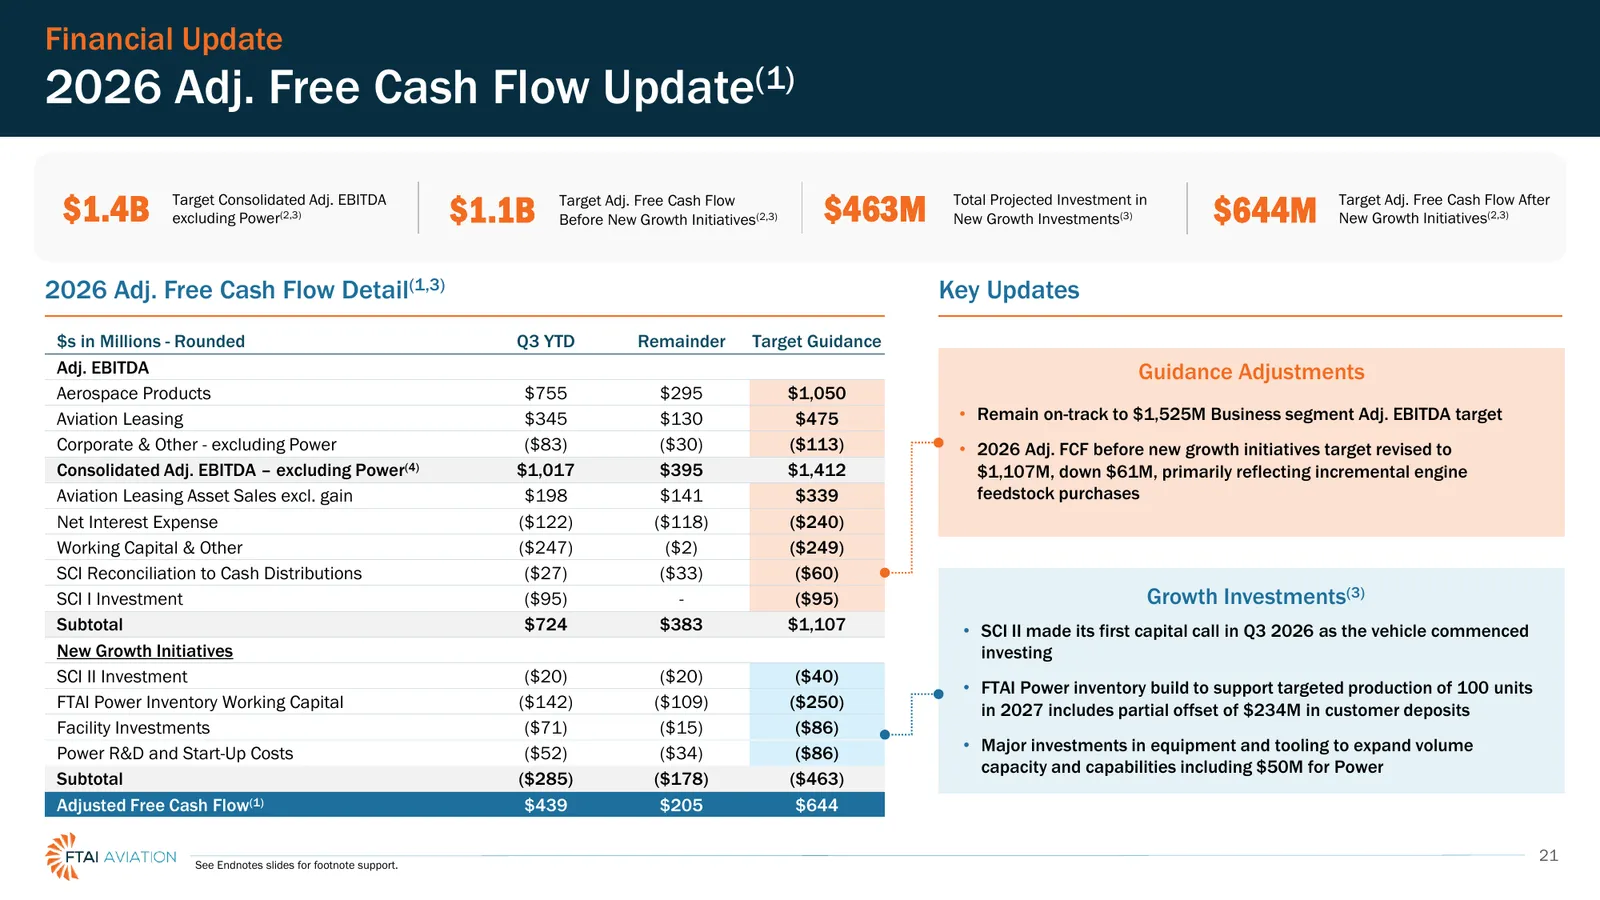
Q3 answered the part the market was most worried about. Aerospace Products delivered $282.4 million of Adjusted EBITDA at a 31% margin, another sequential gain, Leasing recovered to $104.0 million from $88.2 million as Strategic Capital income passed half of the segment, and management reaffirmed every 2026 and 2027 line. It then announced plans for a $500 million accelerated repurchase with RBC and doubled the authorization to $1.0 billion, after buying about $80 million at $178.73 a share since September 15. Q3 also changed the yardstick: Adjusted EBITDA now adds back FTAI Power's pre-commercial R&D, $22.0 million in Q3, which recast Q2 from $291.4 million to $303.5 million.
The part Q3 did not fix is cash, and it is the real argument about this stock. FTAI's income statement books a profit when a rebuilt engine or module is sold; its cash flow statement shows the engines it bought to feed the next sale sitting in inventory, and the aircraft it bought sitting in investing. Operating cash flow was −$310.7 million in FY25 on $477.5 million of net income to shareholders and $1,190.9 million of Adjusted EBITDA, and −$265.3 million in H1 2026 on $251.8 million of net income and $617.0 million of Adjusted EBITDA. Inventory rose from $1,193.8 million at December 31 to $1,932.3 million at September 30. The company's adjusted free cash flow closes that gap by adding back asset-sale proceeds, $339 million of them in the 2026 target.
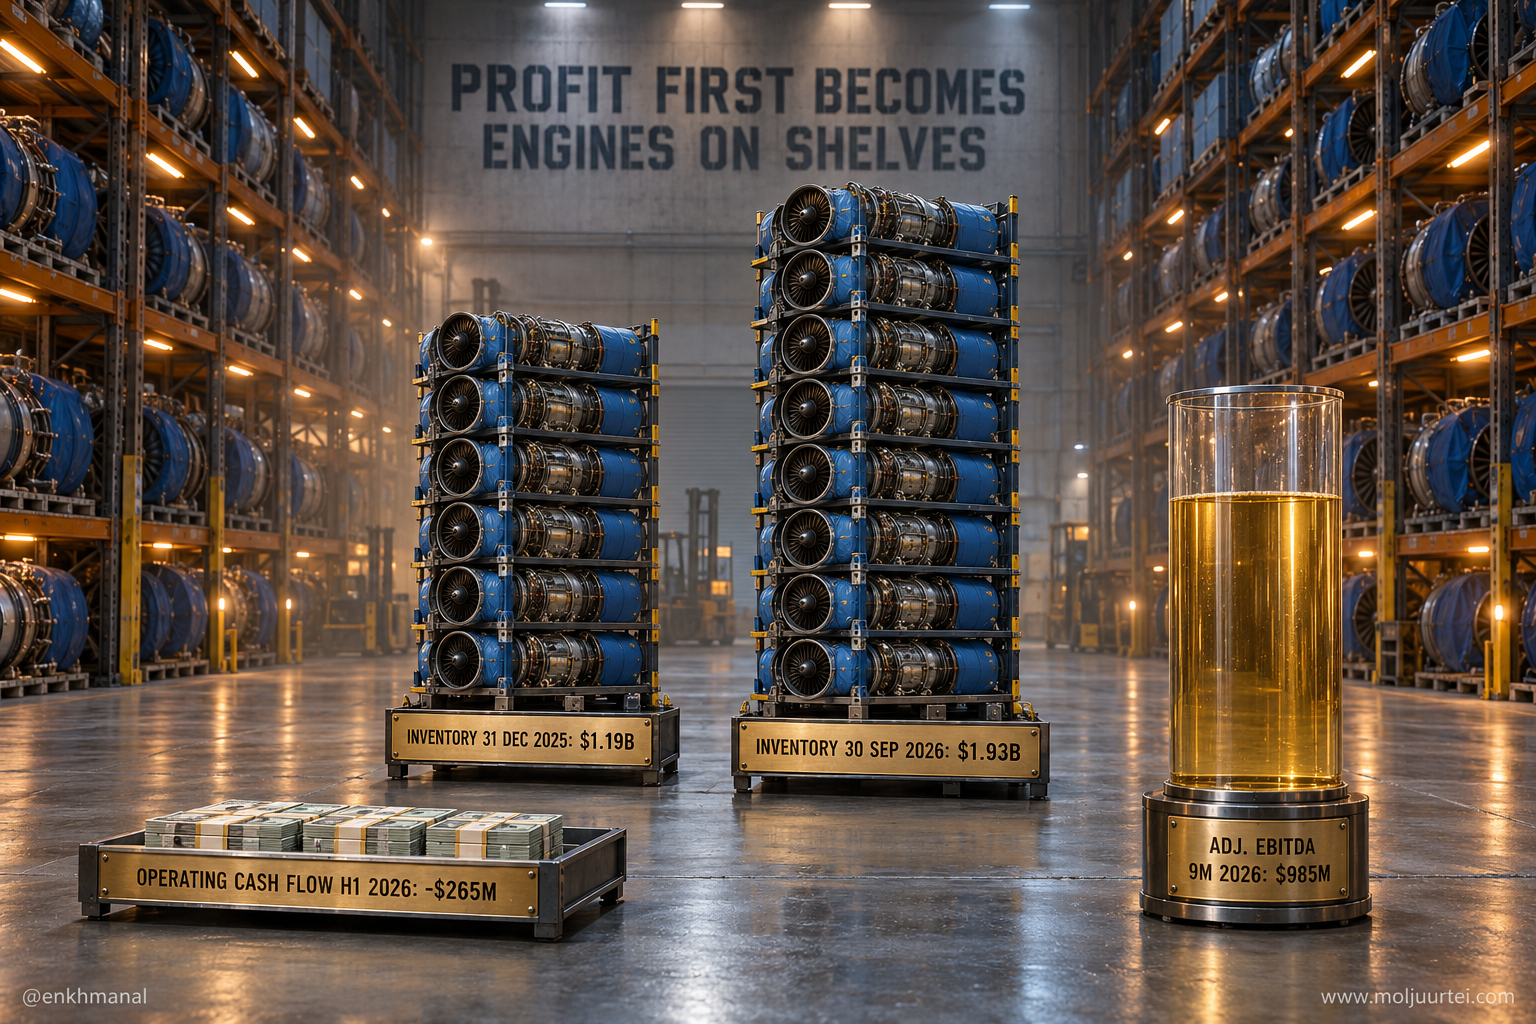
Inventory is the bet, not the accident. The CFO's own history makes the point: about $0.5 billion of inventory two years ago preceded $1.9 billion of Aerospace revenue in 2025, and just under $1 billion a year ago is preceding about $3.5 billion this year. He is planning on roughly two inventory turns a year from here. The asset-light shift means aircraft purchases now land in Strategic Capital rather than on FTAI's balance sheet, and $234 million of Power deposits arrived in Q3 ahead of deliveries. Those are the two changes that should turn adjusted free cash flow into something closer to GAAP free cash flow in 2027; management has not yet given the number.
This is also where the 2025 short reports pointed. Muddy Waters argued in January 2025 that FTAI presented whole-engine sales as module sales and that depreciated engines moved in from the leasing book flattered Aerospace margins; Snowcap followed with a similar case. Since then the auditor changed from EY to KPMG, which signed a clean FY25 opinion with effective internal controls, FTAI now reports module production every quarter, and a securities class action (Shannahan v. FTAI, S.D.N.Y.) was described in the October 29 research as awaiting a ruling on a motion to dismiss filed in November 2025. The margin step from about 35% to about 30% fits management's large-airline explanation; it is also what one would expect if cheap feedstock from the leasing book were running out. The filings cannot separate the two, so we treat margin as the number to watch rather than a settled fact.
Management & Track Record — operators with a mixed guide record
The team is Fortress-trained and long-tenured at the top, newly reshuffled in finance, and its record on guidance splits cleanly by metric: volumes beat, margins and cash did not.
The record we can check is the guidance walk. Module targets went from 1,000 to 1,050 to 1,200 for 2026 and the company is on pace. Segment EBITDA for 2026 went from $1,525 million to $1,625 million in February, helped by insurance recoveries on aircraft lost in Russia, and back to $1,525 million in July. The Aerospace margin target went from 40% plus to 30%, first Mod-1 deliveries moved from late 2026 into 2027, and adjusted free cash flow after growth went from $915 million to $878 million to $644 million. A team that keeps beating on volume while giving back margin and cash is telling us what it optimizes for.
Risks & What Breaks It
Evidence that would weaken the thesis includes a 2027 free-cash-flow outlook below roughly half of EBITDA or Aerospace margins below 28% for two quarters. These are analytical sensitivities: persistent cash shortfalls would require more weight on cash generation than on adjusted profit.
Price Setup — Levels, Technicals & Options
The print took $FTAI back above its 50-day average for the first time since summer. It closed October 28 at $167.14 under a falling 50-day of $179.48, a 100-day of $205.34 and a 200-day of $232.54, and traded near $190 on October 29, up about 14%. The 52-week range runs from about $147 on October 23 to $323.51 in February, so the stock sits in the lower third of its range after the gap.
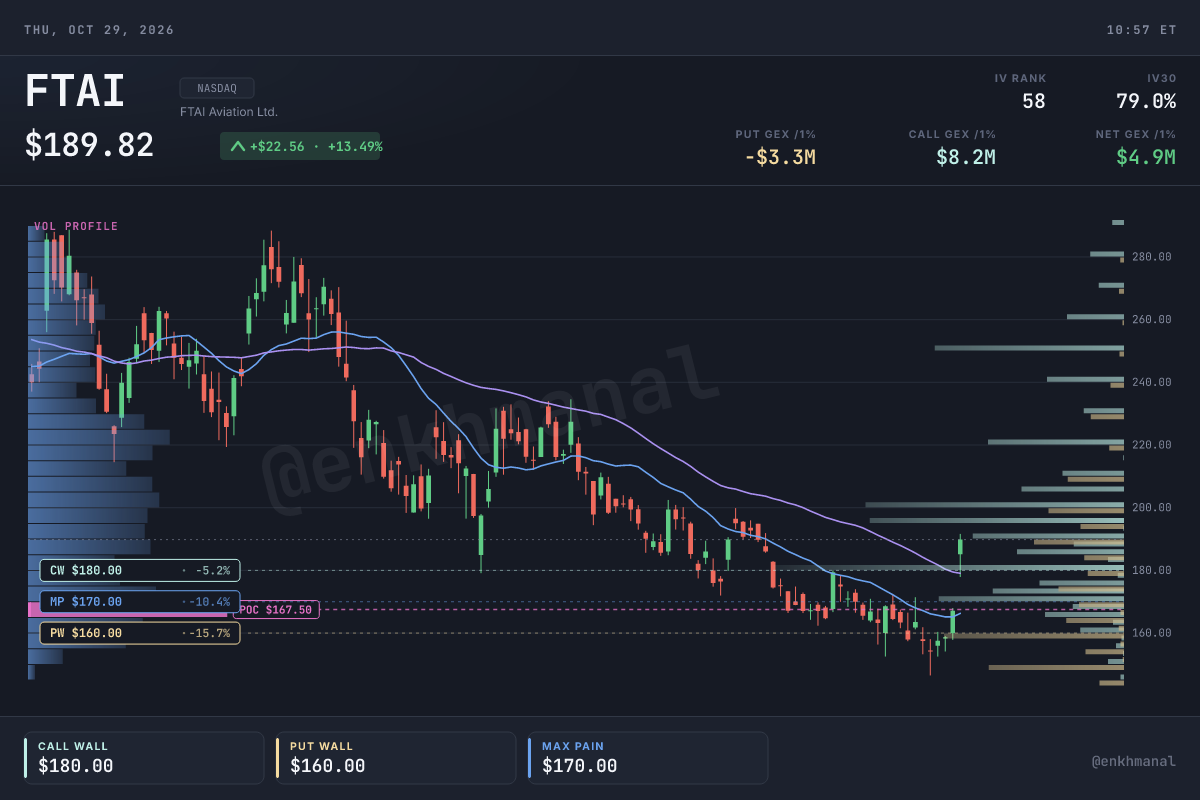
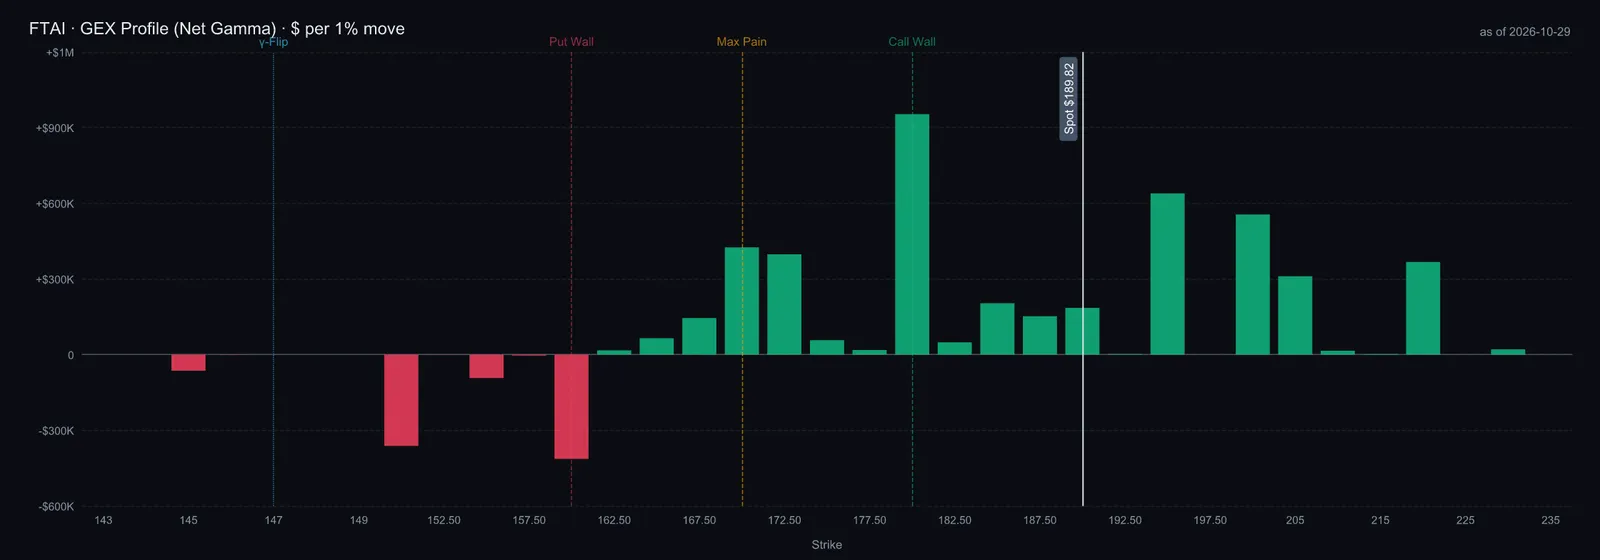
The October 28 pre-results options snapshot showed a call wall at $180, a put wall at $160, max pain at $170 and gamma flip at $150. Net gamma was slightly positive at $1.8 million and the put/call open-interest ratio was 0.52. These are modeled position concentrations, not guaranteed barriers. The October 29 price gap crossed the old call wall, so the old levels should not be carried forward unchanged. November 20 implied volatility was about 79% before results; post-results compression was an expectation, not an observed outcome here. The 200-day average near $232 was a trend reference; a crossing alone would not prove the 2027 business outlook.
Valuation & House View
At $190.50, $FTAI is worth about $19.5 billion in equity on 102.4 million shares, and about $22.6 billion including $3.07 billion of net debt and $65 million of preferred. That is 16.0 times the $1,412 million of 2026 consolidated Adjusted EBITDA excluding Power that management guides, and roughly 10.5 times 2027 if the $2.3 billion segment guide lands with about $150 million of corporate cost (our estimate). On trailing GAAP numbers it trades at 41.5 times earnings, the 15th percentile of its own five-year range and below a 53.7 times median, with a trailing PEG of 0.67; $GE sits at 36.1 times, $HEI at 53.7 times, $SARO at 24.4 times and $AER at 12.3 times.
A dated cash-flow sensitivity used a 1.5% terminal growth rate and an 11× exit multiple, giving $260.19 per share under perpetuity and $300.38 under the multiple method, with bear and bull values of $173.55 and $320.54. These are assumption-dependent estimates, distinct from the end-2028 scenarios below. Revenue was an analyst assumption because the company guides EBITDA. The model used depreciation at 12% of revenue versus 4.4% in Q3, terminal capital spending below depreciation and selling/general/administrative expense at 7% of sales. Those choices, the cash-conversion gap and the exit multiple materially affect the result. They do not establish current fair value.
These are analyst scenarios, not company forecasts. Price = (EBITDA × multiple − net debt − preferred equity) ÷ assumed shares. With illustrative 20/50/30 weights, they give about $256.10, or 34.4% above the dated $190.50 reference. Probabilities are judgment, not measured odds; a single severe setback could also produce losses.
FTAI offers a credible growth mechanism: an aging fleet needs engine time, and a stocked module network can shorten downtime. Q3 supports volume growth and a margin recovery; the Power opportunity remains pre-delivery. The December 10 investor meeting is a test of cash-conversion expectations, followed by first Mod-1 deliveries planned in 2027. The end-2028 base scenario is $255.35 under the stated assumptions; inventory, margins and financing determine whether that opportunity reaches shareholders.